Recomienda este artículo a tus amigos:
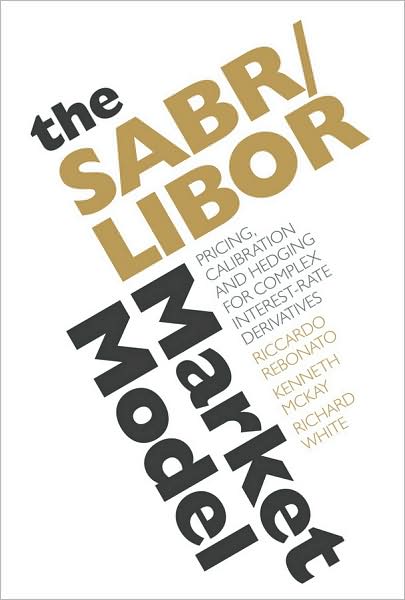
The SABR / LIBOR Market Model: Pricing, Calibration and Hedging for Complex Interest-Rate Derivatives Rebonato, Riccardo (Royal Bank of Scotland Group, UK)
Precio
Mex$ 2.281
sin IVA
Pedido desde almacén remoto
Entrega prevista 2 - 18 de nov.
 Los regalos de Navidad se podrán canjear hasta el 31 de enero

Recibe notificaciones sobre nuevos lanzamientos de Rebonato, Riccardo (Royal Bank of Scotland Group, UK)
Nuestros clientes opinan:
Añadir a tu lista de deseos de iMusic
The SABR / LIBOR Market Model: Pricing, Calibration and Hedging for Complex Interest-Rate Derivatives
Rebonato, Riccardo (Royal Bank of Scotland Group, UK)
This book presents a major innovation in the interest rate space. It explains a financially motivated extension of the LIBOR Market model which accurately reproduces the prices for plain vanilla hedging instruments (swaptions and caplets) of all strikes and maturities produced by the SABR model.
296 pages, black & white tables, figures
| Medios de comunicación | Libros Hardcover Book (Libro con lomo y cubierta duros) |
| Publicado | 20 de abril de 2009 |
| ISBN13 | 9780470740057 |
| Editores | John Wiley & Sons Inc |
| Páginas | 304 |
| Dimensiones | 177 × 252 × 22 mm · 660 g |
| Lengua | Inglés |




